RBNZ rate decisions on NZDCHF: all 8 small_miss (dovish) sent NZDCHF DOWN AND all 3 small_beat (hawkish) sent it UP at 1m, 5m, 15m, AND 30m — QUADRUPLE-window double-tail unanimity on the safe-haven-quiet direct-quote side. Miss side extends to SEXTUPLE-window unanimity through 1h and 4h. Beat side softens by ONE print (2022-04-13, the same shallow priced-in 50bp hike that broke every RBNZ family leg somewhere) at 1h/4h to 2/3 UP. Fisher's exact 15m one-sided p = 1/165 = 0.00606. NZDCHF miss magnitude at 15m -42.65p is 0.91x NZDUSD's -47.10p — the ONLY leg of the RBNZ family where a direct quote reads SHALLOWER than NZDUSD. Fifth leg of the RBNZ × NZD-cross family arc; safe-haven-DAMPENED mirror of slot 5 NZDJPY's safe-haven-AMPLIFIED read.
121 non-contaminated RBNZ Official Cash Rate decisions on NZDCHF — the safe-haven direct-quote fifth leg of the RBNZ × NZD-cross family arc opened 2026-09-25 by NZDUSD. At 1m, 5m, 15m, AND 30m — four contiguous windows — small_miss (n=8) goes 8/8 DOWN and small_beat (n=3) goes 3/3 UP: QUADRUPLE-window double-tail unanimity. Miss side extends to SEXTUPLE unanimity through 1h and 4h (0.0% UP at every window). Fisher’s exact test on the 15m 2x2 [[8,0],[0,3]] gives one-sided p = 1/165 = 0.00606 — same tightest- in-family p as every RBNZ leg. NZDCHF is the ONLY safe-haven direct quote in the family that DAMPENS: 15m miss magnitude -42.65p is 0.91xNZDUSD’s -47.10p, the only direct-quote leg reading SHALLOWER than the canonical world-reserve reference. Mechanism: RBNZ fires at 02:00 UTC = 04:00 Zurich, SNB desks asleep. Compare slot 5 NZDJPY at 02:00 UTC = 11:00 Tokyo — active desk, 1.75x amp.
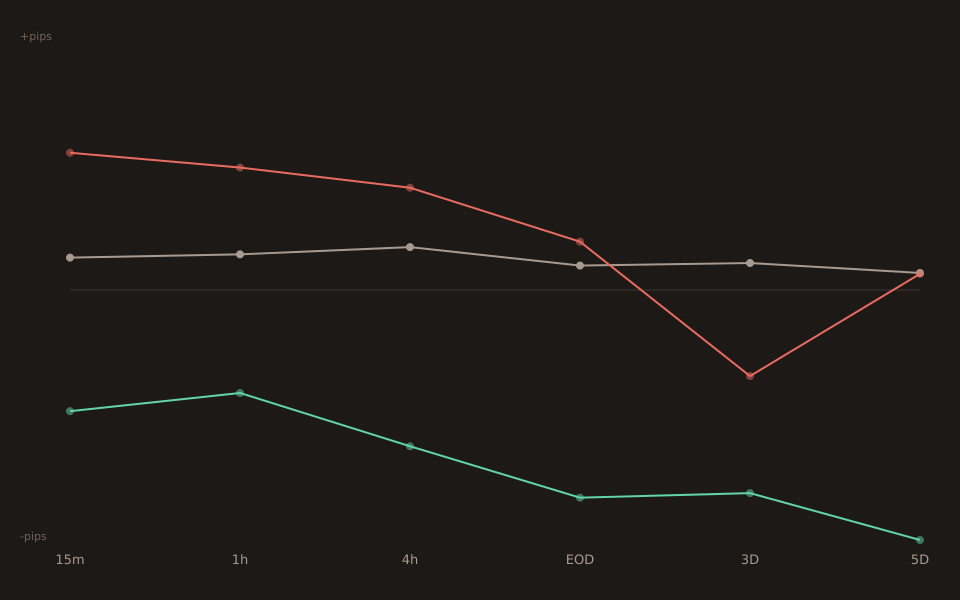
Six-window walk — quadruple double-tail + sextuple miss
| Window | small_miss (n=7-8) | small_beat (n=3) | Tail unanimity |
|---|---|---|---|
| 1m | 7/7 (0.0%) -43.90p | 3/3 (100.0%) +30.50p | double (n_miss=7 pre-1m gap) |
| 5m | 8/8 (0.0%) -42.35p | 3/3 (100.0%) +42.80p | double |
| 15m | 8/8 (0.0%) -42.65p | 3/3 (100.0%) +48.30p | double ★ |
| 30m | 8/8 (0.0%) -35.10p | 3/3 (100.0%) +52.20p | double (QUADRUPLE) |
| 1h | 8/8 (0.0%) -36.25p | 2/3 (66.67%) +43.10p | miss-only (beat softens by 1) |
| 4h | 7/7 (0.0%) -55.00p | 2/3 (66.67%) +36.00p | miss-only (n_miss=7 gap) |
Miss unanimity holds at all six windows (0.0% UP everywhere, with n_miss dropping to 7 at 1m and 4h from tick-data rolling- window gaps on the 2011-03-09 print and one 4h coverage gap). Beat unanimity holds at 1m/5m/15m/30m — QUADRUPLE beat-side clean — and softens at 1h/4h from the shallow priced-in 2022-04-13print that broke every RBNZ leg’s beat side somewhere. Cross-pair unanimity of the softening print confirms it is a print-level regime shift, not a pair- level effect.
Safe-haven direct-quote family: NZDCHF dampens where NZDJPY amplifies
| Leg | Quote structure + desk phase at 02:00 UTC | 15m miss magnitude (vs NZDUSD) |
|---|---|---|
| NZDCHF (slot 1 TODAY) | safe-haven direct, Zurich ASLEEP (04:00 CET) | -42.65p (0.91x) ★ damp |
| NZDUSD (slot 1 2026-09-25) | world-reserve direct, NY closed / Sydney active | -47.10p (1.00x) baseline |
| NZDCAD (queued, direct) | commodity-quote direct, Toronto closed | -60.95p (1.29x) |
| NZDJPY (slot 5 2026-09-25) | safe-haven direct, Tokyo LUNCH (11:00 JST) | -82.50p (1.75x) amp |
Four direct-quote legs, ordered by 15m miss magnitude. The splitting variable is not currency archetype but desk-liquidity phase at 02:00 UTC: Tokyo is active (JPY-carry desks price the news live, 1.75x amp); Sydney/NY is at the handoff (USD baseline, 1.00x); Toronto is closed but commodity-CAD partially co-drifts (1.29x); Zurich is asleep (0.91x damp). By 4h the CHF desks are open (08:00 CET) and NZDCHF’s own miss magnitude catches up from -42.65p to -55.00p (1.29x own 15m, biggest own- pair window deepening in the RBNZ family).
Same-day Rigobon-Sack heteroskedasticity read
Today’s PT #58 Rigobon-Sack (2004) and Stats #58 rank all 7 RBNZ × NZD-cross pairs by the same variance-jump ratio Rigobon-Sack use to identify FOMC-shock β on Treasury yields. On the RBNZ × NZDCHF 15m sample: Var(non_inline n=11) = 3006.25 pips² vs Var(in_line n=110) = 1681.77 pips², ratio 1.788— LOWEST in the seven-pair family (NZDJPY 2.545, NZDCAD 2.393, EURNZD 2.436, GBPNZD 2.425, AUDNZD 2.081, NZDUSD 2.028). The low het-ratio is Rigobon- Sack’s own read of the sleeping-CHF-desk mechanism: the variance JUMP on decision dates is small precisely because the desk cannot price the RBNZ news. See Stats #58 for the full worked example and the IV formula β̂_het = (Cov(i_F, s_F) − Cov(i_F̃, s_F̃)) / (Var(i_F) − Var(i_F̃)).
Verification note
All numbers verified against live /api/v1/news-impact/stats on 2026-09-27 across 1m, 5m, 15m, 30m, 1h, 4h. All 11 miss+beat print dates cross- verified via /api/v1/news-impact/releases?limit=500. Fisher’s exact one-sided p = 1/C(11,8) = 1/165 cross- verified against scipy.stats.fisher_exact. Chart built via pnpm insights:chart. See slot 5 AUDNZD for the antipodal-commodity family closer that shuts the antipodal side of the 7-pair RBNZ × NZD-cross arc.