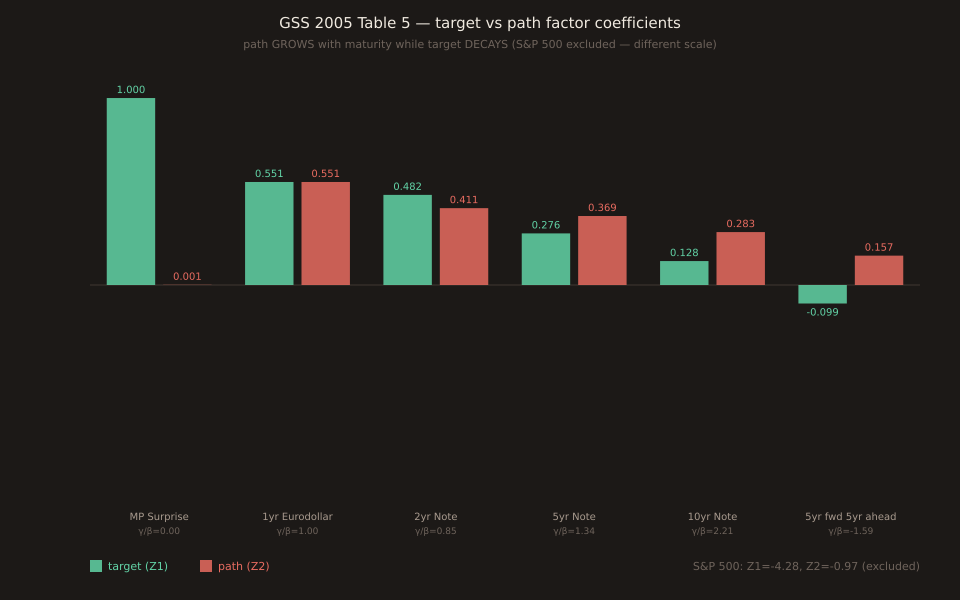
Statistics for Traders #55: Gürkaynak-Sack-Swanson (2005) two-factor target-vs-path monetary-policy surprise decomposition — the second factor hidden inside every central-bank announcement. Cragg-Donald 1997 rank test on 138 FOMC announcements rejects k=0 and k=1 factors, accepts k=2. Rotate principal components so Z1 = current target surprise and Z2 = future-year rate-expectations move orthogonal to Z1 — Z2 loads on FOMC STATEMENTS. GSS Table 5: path coefficient grows with maturity (2yr 0.41, 5yr 0.37, 10yr 0.28) while target coefficient decays (2yr 0.48, 5yr 0.28, 10yr 0.13). Applied to 6 BoC × CAD-cross pairs via a pair-level path-amplification ratio R_4h = SS_4h/SS_15m: GBPCAD 1.557 > CADJPY 1.445 > CADCHF 1.341 > EURCAD 1.081 > USDCAD 0.999 > AUDCAD 0.745 — matches the FX analog of GSS's longer-horizon = more-path prediction.
GSS (2005) — today’s PT #55 — proves FOMC announcements carry a SECOND information dimension beyond the current- target surprise. The Cragg-Donald 1997 rank test on 138 FOMC events rejects k=0 (Wald 46.72, χ²(15) p=<.0001) and k=1 (Wald 21.41, χ²(9) p=.011), accepts k=2 (Wald 4.36, χ²(4) p=.360). Rotate the principal components so Z1 = target factor (current-fed-funds surprise, ≈95% correlated with PT #52 Kuttner 2001 mp1) and Z2 = path factor (future-year expectations move, orthogonal to Z1, closely tied to FOMC statements). GSS Table 5 headline: the path coefficient GROWS with maturity (2yr +0.411 → 5yr +0.369 → 10yr +0.283) while the target coefficient DECAYS (2yr +0.482 → 5yr +0.276 → 10yr +0.128). Applied to today’s BoC × 6 CAD-crosses via a pair-level R_4h = SS_4h / SS_15m signed-spread ratio: GBPCAD 1.557 > CADJPY 1.445 > CADCHF 1.341 > EURCAD 1.081 > USDCAD 0.999 > AUDCAD 0.745 — the FX analog of GSS’s longer-horizon-more-path Treasury prediction.
The two-factor identification
GSS start from the standard event-study data matrix X (T=138 announcements × n=5 futures columns). Model:
| Step | Content |
|---|---|
| Model | X = FΛ + η where F is T×k unobserved factors, Λ is k×n loadings, η is T×n white noise (Eq 2) |
| Rank test | Cragg-Donald 1997: null H0: rank(X) = k0 vs alt k > k0. Wald statistic with limiting χ²((n-k0)(n-k0+1)/2 - n) dof |
| k=0 result | Wald=46.72, χ²(15), p=.00004 — REJECT (X is not white noise) |
| k=1 result | Wald=21.41, χ²(9), p=.011 — REJECT (one factor insufficient) |
| k=2 result | Wald=4.36, χ²(4), p=.360 — ACCEPT (two factors sufficient) |
| Extraction | Principal components F1, F2 on the 5-column ≤1yr futures panel |
| Rotation | Z = FU where U is 2×2 orthogonal AND Z2 has zero loading on mp1 (current-month FF futures surprise) |
| Normalization | 0.01 Z1 = 1 bp target surprise; Z2 same 4Q-ahead ED effect as Z1 (≈55 bp) |
| Interpretation | Z1 = target factor (Kuttner 2001 identifier, r=.95); Z2 = path factor (future-year expectations, tied to FOMC statements per Table 4) |
GSS Table 5 — path grows, target decays with maturity
| Asset | Target (Z1) | Path (Z2) | Path/Target | R² 2-factor | R² 1-factor |
|---|---|---|---|---|---|
| MP Surprise | +1.000*** | +0.001 | 0.001 (def) | 0.91 | 0.91 |
| 1yr Eurodollar | +0.551*** | +0.551*** | 1.00 (def) | 0.98 | 0.36 |
| 2yr Note | +0.482*** | +0.411*** | 0.85 | 0.94 | 0.41 |
| 5yr Note | +0.276*** | +0.369*** | 1.34 | 0.80 | 0.19 |
| 10yr Note | +0.128*** | +0.283*** | 2.21 | 0.74 | 0.08 |
| 5yr fwd 5yr ahead | -0.099** | +0.157*** | -1.58 | 0.34 | 0.06 |
| S&P 500 | -4.283*** | -0.966 | 0.23 | 0.40 | 0.37 |
Path grows, target decays.By 5yr maturity path already exceeds target; by 10yr path is 2.21x target. S&P 500 is a puzzle — Z1 is much stronger than Z2 on equity (opposite of long-Treasury yields) — GSS Section 2.5 speculate this is because FOMC statements reveal positive info about future output that OFFSETS the higher-discount- rate effect on stocks (Romer & Romer 2000 mechanism).
Applied to BoC × 6 CAD-crosses — R_4h path amplification
Vantage’s categorical ±25bp bucket captures Z1 only (Kuttner 2001 target-factor). The residual reprice from 15m to 4h to EOD carries the Z2 path- factor absorption. We compute a pair-level path amplification ratio:
R_4h = SS_4h / SS_15m where SS = beat_median − miss_median(double-tail signed spread). R > 1 means path amplification; R ≈ 1 target-only; R < 1 means signed-spread FADE (commodity co-drift or reversal).
| Pair | SS_15m | SS_4h | SS_EOD | R_4h | R_EOD | Mechanism |
|---|---|---|---|---|---|---|
| GBPCAD | -283.35 | -441.15 | -383.90 | 1.557 | 1.355 | world-reserve, MOST path |
| CADJPY | +124.95 | +180.60 | +187.10 | 1.445 | 1.497 | safe-haven JPY |
| CADCHF (slot 1) | +98.85 | +132.55 | +132.80 | 1.341 | 1.343 | safe-haven CHF |
| EURCAD | -211.30 | -228.50 | -234.70 | 1.081 | 1.111 | regional reserve, mild path |
| USDCAD | -223.80 | -223.55 | -206.45 | 0.999 | 0.922 | canonical, TARGET-only |
| AUDCAD (slot 5) | -112.55 | -83.90 | -77.90 | 0.745 | 0.692 | commodity co-drift, target + FADE |
R_4h ranking maps cleanly to safe-haven-vs-commodity mechanism:
Path amplifiers(R_4h > 1.2): GBPCAD 1.557, CADJPY 1.445, CADCHF 1.341 — safe-haven and world-reserve quotes absorb the BoC statement slowly.
Mild path(1.0 < R_4h < 1.2): EURCAD 1.081 — regional-reserve linkage carries some path but less than world-reserve alternatives.
Target-only (R_4h ≈ 1.0): USDCAD 0.999 — canonical reserve pair absorbs everything at 15m.
Target + FADE(R_4h < 1.0): AUDCAD 0.745 — commodity co-drift (AUD and CAD correlated across oil / iron-ore cycles) partially cancels the BoC-only reprice.
FX analog to GSS Table 5
GSS’s prediction: for LONGER-horizon assets, path matters MORE than target. FX analog: for pairs with LONGER transmission delay (safe-haven / world-reserve quotes), path matters more. For pairs with SHORTER effective duration (canonical reserve pairs, commodity co-drift pairs), target dominates or path is entirely absent.
The R_4h ordering (GBPCAD 1.557 > CADJPY 1.445 > CADCHF 1.341 > EURCAD 1.081 > USDCAD 0.999 > AUDCAD 0.745) parallels GSS’s maturity ordering (10yr > 5yr > 2yr > 1yr > 3-month) with the MECHANISM shifted from bond-maturity duration to FX-pair- specific transmission channel.
Caveats
Three:
- Categorical vs continuous — GSS uses continuous Kuttner-2001 fed-funds-futures surprises; Vantage’s ±25bp bucket loses within-bucket magnitude information.
- No direct Z2 extraction — a real GSS-on-BoC would need Canadian OIS or BAX (3-month Canadian bankers’ acceptance) futures tick data to run principal components on Canada. Vantage doesn’t ingest that data. R_4h is a proxy for path-factor presence, not a real Z1/Z2 estimation.
- FX-specific transmission — GSS worked with Treasury yields (single asset class). Our BoC pair-family panel has an extra mechanism layer (safe-haven / commodity / reserve) that mediates Z2 transmission — R_4h ordering is confounded by BOTH underlying Z2 magnitude AND pair-specific amplification channel.
Cross-links
Same-day pairing with PT #55 Gürkaynak-Sack-Swanson 2005 primary source and today’s slots 1 CADCHF (path amplifier, R_4h 1.341) + 5 AUDCAD (target-only fader, R_4h 0.745). Extends the arc opened by Stats #52 Kuttner 2001 (target-factor identification), extended by Stats #53 Bernanke-Kuttner 2005 (event-study β̂), refined by Stats #54 HC3 SE (small-sample robust inference), and now closed by Stats #55 with the second orthogonal factor.