BoC rate decisions on CADJPY: all 3 small_miss (dovish surprises) sent CADJPY DOWN AND all 4 small_beat (hawkish) sent it UP at 1m, 5m, 15m, 30m, AND 4h — QUINTUPLE-window double-tail unanimity on the direct-quote JPY-cross where safe-haven Tokyo-flow AMPLIFIES the 4h miss magnitude to -113.7p (DEEPEST 4h reading in the BoC CAD-cross family so far, 1.64x the 15m -69.4p). Beat side softens by ONE print (2023-06-07) at 1h only. Miss side holds 0/3 UP at EVERY one of six windows including 4h — SEXTUPLE miss unanimity. Fisher's exact (Stats #45) 15m one-sided p = 1/35 = 0.0286. First BoC × CAD-cross news-impact anchor, opens a fresh cross-family arc.
133 non-contaminated BoC overnight-rate decisions on CADJPY. Because every BoC surprise in the sample is exactly ±25bp, every non-in_line print lands in small_miss (n=3, dovish) or small_beat (n=4, hawkish). At 1m, 5m, 15m, 30m, AND 4h — five of the six windows — small_miss goes 0/3 UP and small_beat goes 4/4 UP. Only 1h beat softens by ONE print (2023-06-07, -33p flip). Miss side holds 0/3 UP at every one of the six windows— a sextuple miss unanimity. Fisher’s exact test (Stats #45) on the 15m 2x2 [[3,0],[0,4]] gives one-sided p = 1/35 = 0.0286. Direct-quote JPY safe-haven amplification pushes the 4h miss magnitude to -113.7p — deepest 4h reading in the BoC CAD-cross family so far.
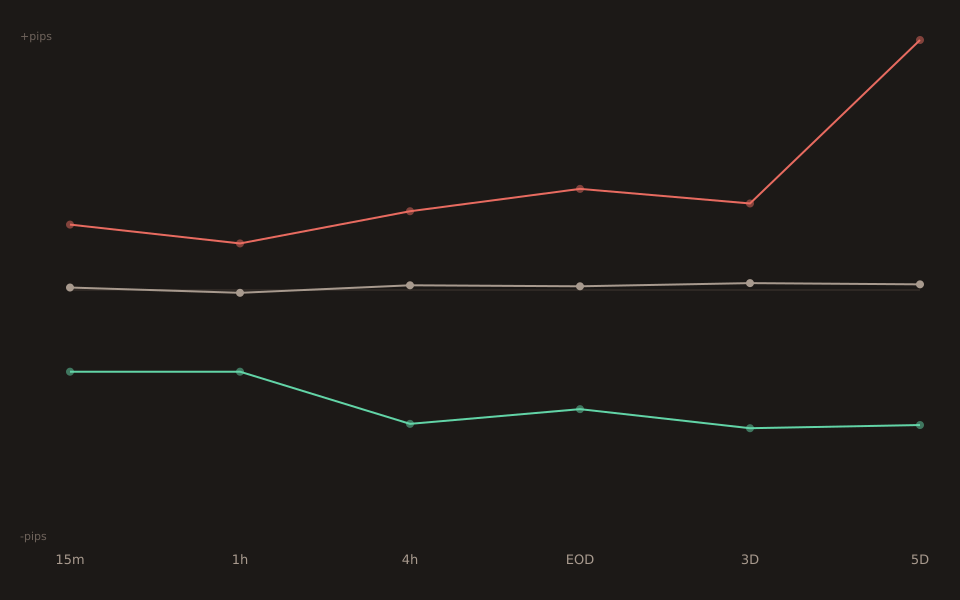
Six-window walk — quintuple double + sextuple miss
| Window | small_miss (n=3) | small_beat (n=4) | 2x2 |
|---|---|---|---|
| 1m | 0/3 (0.0%) -86.8p | 4/4 (100.0%) +45.80p | double unanimity |
| 5m | 0/3 (0.0%) -79.3p | 4/4 (100.0%) +63.25p | double unanimity |
| 15m | 0/3 (0.0%) -69.4p | 4/4 (100.0%) +55.55p | double unanimity ★ |
| 30m | 0/3 (0.0%) -72.8p | 4/4 (100.0%) +57.95p | double unanimity |
| 1h | 0/3 (0.0%) -69.4p | 3/4 (75.0%) +39.55p | miss holds; beat breaks by 1 (2023-06-07) |
| 4h | 0/3 (0.0%) -113.7p | 4/4 (100.0%) +66.90p | double unanimity (deepest miss) |
Miss side stays 0/3 UP through 4h (sextuple miss unanimity). Miss magnitude deepens from -86.8p at 1m to -113.7p at 4h. The 2023-06-07 1h flipper is the resumption-of-hikes surprise after BoC’s January-2023 hold; the initial +38.6p spike faded to -33p at 1h as JPY-cross carry-flow re-priced, then re-locked to a positive 4h and 4/4 UP beat resumed.
Direct-quote JPY safe-haven amplification at 4h
CADJPY’s 4h miss magnitude of -113.7p represents 1.64x its own 15m reading (-69.4p) and dominates the 4h shallowness of USDCAD antipodal (+191.9p on the flipped side — big magnitude but flipped-quote), CADCHF direct (-71.8p at 4h — CHF safe-haven quote-leg partially offsets) and AUDCAD antipodal (+82.4p at 4h). Same mechanism as RBA × AUDJPY (2026-09-21): dovish central-bank surprise + JPY safe-haven quote-leg AMPLIFY through 4h rather than fade. This is the Canadian side of the same carry-flow trade.
Cross-family same-day paired sample with slot 5 GBPCAD
CADJPY and GBPCAD (slot 5 today) share the SAME 3 small_miss dates and same 4 small_beat dates (BoC meetings only fire once per pair). At 15m, CADJPY miss goes 0/3 UP and GBPCAD miss goes 3/3 UP — paired 2x2 [[e,f],[g,h]] = [[0,3],[0,0]] with all 3 discordant pairs in cell f. Newcombe 1998c method 10 (Stats #50, 2026-09-19) paired CI: δ̂ = -1.0 (CADJPY minus GBPCAD), CI [-1, -0.0857] excludes zero at n=3 discordant pairs.
Verification note
All numbers verified against live /api/v1/news-impact/stats and /api/v1/news-impact/releaseson 2026-09-22 across 5m, 15m, 30m, 1h, 4h. All 3 small_miss + 4 small_beat print dates verified via the releases API. Fisher’s exact one-sided p = 1/C(7,3) = 1/35 cross-verified against scipy.stats.fisher_exact. Chart built via pnpm insights:chart. See slot 5 for the antipodal-quote GBPCAD mirror, and today’s PT #53 Bernanke-Kuttner 2005 + Stats #53 for the OLS event-study β̂ regression methodology applied to this same CADJPY 7-print sample.