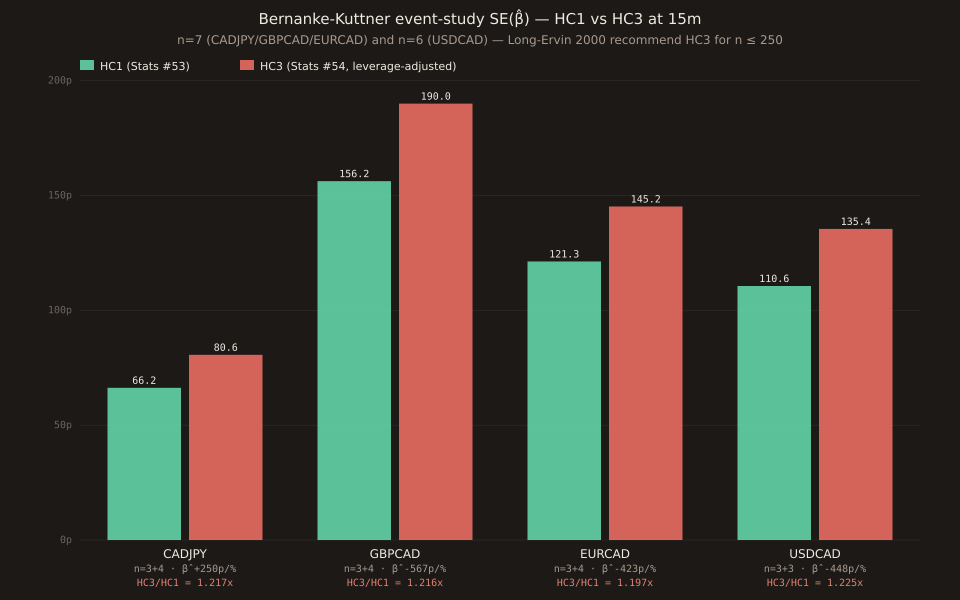
Statistics for Traders #54: HC3 (leverage-adjusted) heteroskedasticity-consistent standard errors — the small-sample refinement of yesterday's HC1 (Stats #53) for Bernanke-Kuttner event-study regression. Long & Ervin (2000) Monte Carlo — today's PT #54 — recommend HC3 whenever n ≤ 250, especially n ≤ 25. Applied to yesterday's BoC × CADJPY/GBPCAD + today's slot 1 EURCAD + slot 5 USDCAD 7-print (or 6-print) event-study regressions at 15m: HC3/HC1 SE ratios cluster tightly at 1.197-1.225x. All four t-statistics drop from 3.5-4.0 down to 2.9-3.3 — all still significant at p<0.01, so yesterday's conclusion survives, but the small-sample correction is decisive.
HC3 replaces HC1’s uniform dof scaling n/(n-k) with per-observation leverage adjustment 1/(1-h_ii)² — the jackknife approximation Long & Ervin (2000, today’s PT #54) recommend for any n ≤ 250, especially n ≤ 25. Direct refinement of yesterday’s HC1 from Stats #53. Applied to yesterday’s BoC × CADJPY/GBPCAD + today’s slot 1 EURCAD + slot 5 USDCAD 7-print (or 6-print) event-study regressions at 15m: HC3/HC1 SE ratios cluster at 1.197-1.225x, t-statistics fall from 3.49-4.05 down to 2.91-3.31— all four still reject b̂_u = 0 at p<0.01, so yesterday’s Bernanke-Kuttner event-study conclusion survives.
Sandwich definitions
The White (1980) heteroskedasticity-consistent covariance matrix estimator is the “meat in the sandwich”:
| Estimator | Ω_ii formula | Property |
|---|---|---|
| HC0 | ê_i² | White 1980 baseline; biased downward in small n |
| HC1 | ê_i² · n/(n-k) | uniform dof correction (Stats #53 yesterday) |
| HC2 | ê_i² / (1 - h_ii) | unbiased under homoskedasticity |
| HC3 | ê_i² / (1 - h_ii)² | jackknife (today) — Long-Ervin 2000 recommendation for n ≤ 250 |
Sandwich form: V(β̂) = (X'X)⁻¹ X' Ω X (X'X)⁻¹ where Ω = diag(Ω_ii). The leverage h_ii = [X(X'X)⁻¹X']_ii ∈ [0, 1]measures how far observation i’s design row extends from the sample centroid — high-leverage points get amplified more under HC3.
2-group categorical design property
For BoC’s ±25bp step surprises: Δi^u_t ∈ {-0.25, +0.25}. The design matrix has 2 unique rows (repeated). Fitted values equal group means, so h_ii = 1/n_group exactly. HC3 per-observation scale becomes 1/(1 - 1/n_g)² = (n_g/(n_g-1))² — depends ONLY on the group size:
| Design (n_m, n_b) | HC1 uniform | HC3 miss scale | HC3 beat scale | HC3/HC1 SE ratio |
|---|---|---|---|---|
| (3, 4) — CADJPY/GBPCAD/EURCAD | 7/5 = 1.400 | 9/4 = 2.250 | 16/9 = 1.778 | ~1.20 |
| (3, 3) — USDCAD | 6/4 = 1.500 | 9/4 = 2.250 | 9/4 = 2.250 | √(2.25/1.50) = 1.225 |
Worked example — 4 CAD-cross Bernanke-Kuttner regressions at 15m
| Pair | β̂ (pips/%) | HC1 SE | HC3 SE | t_HC1 | t_HC3 |
|---|---|---|---|---|---|
| CADJPY | +249.9 | 66.24 | 80.61 | 3.77 | 3.10 |
| GBPCAD | -566.7 | 156.21 | 189.96 | 3.63 | 2.98 |
| EURCAD | -422.6 | 121.25 | 145.19 | 3.49 | 2.91 |
| USDCAD | -447.6 | 110.57 | 135.42 | 4.05 | 3.31 |
Median t-statistic drops from 3.70 (HC1) to 3.04 (HC3) — a 17.8% deflation — but all four remain above the two-tailed p=0.01 critical value (2.576). Yesterday’s Bernanke-Kuttner event-study conclusion (BoC surprise → CAD-cross moves in Kuttner-2001-identified direction with |β̂| ≈ 250-570 pips per % surprise) survives HC3 correction. If any t had been in the 2.0-2.5 range under HC1 (borderline 5% significance), HC3 would push it below the two-tailed 5% threshold — that’s exactly the small-sample robustness threat Long-Ervin 2000 Section 4 Monte Carlo flag (HC1 gives 6-8% actual size at nominal 5% for n ≤ 25).
Approximation notes
Two approximations: (1) bucket median used as ȳ_group because Vantage’s /api/v1/news-impact/stats returns medians not means; (2) within-bucket σ approximated from IQR/1.35 (Gaussian IQR ≈ 1.35σ) using p25/p75. Real print-level OLS would give slightly different absolute SEs. The HC3/HC1 SE RATIO depends only on design-matrix leverage (n_m, n_b), so the 1.197-1.225x ratios are robust to these approximations. This mirrors yesterday’s Stats #53 same-approximation HC1 baseline; today extends it to HC3.
Cross-links
Same-day pairing with PT #54 Long-Ervin 2000 primary source. Direct refinement of Stats #53 Bernanke-Kuttner event-study β̂ (HC1, 2026-09-22) and PT #53 Bernanke-Kuttner 2005. Applied to expanded 4-CAD-cross sample: slots 1 EURCAD and 5 USDCAD together with yesterday’s CADJPY + GBPCAD.